

Mortgage help
Mortgage declined after agreement in principle?
An agreement in principle is not a guarantee. If a lender has declined your full application, there may still be options. Tony can look at why it happened and which lenders may be a better fit for your circumstances.
Talk to TonyAt a glance
- An agreement in principle is not a mortgage offer
- Access to 100+ lenders and around 28,000 deals
- Rated 5.0 from 235+ Google reviews
Your home may be repossessed if you do not keep up repayments on your mortgage.
There may be a fee for mortgage advice. The actual amount you pay will depend upon your circumstances. The fee is up to 1% but a typical fee is 0.3% of the amount borrowed.
Why this can happen
An agreement in principle is an early indication from a lender, usually based on a quick check. The full application is where documents, credit history and the property are checked in detail. These are some common reasons for a decline.
What to do next
Sensible first steps
- Ask the lender or your adviser for the reason, so you know what needs to change.
- Avoid making new credit applications while you work out what happened, as lenders can see recent applications.
- Check your credit file for errors, and gather up-to-date documents.
- Speak to a mortgage adviser before applying again. Different lenders look at the same situation in different ways, and Tony can search over 100 of them.
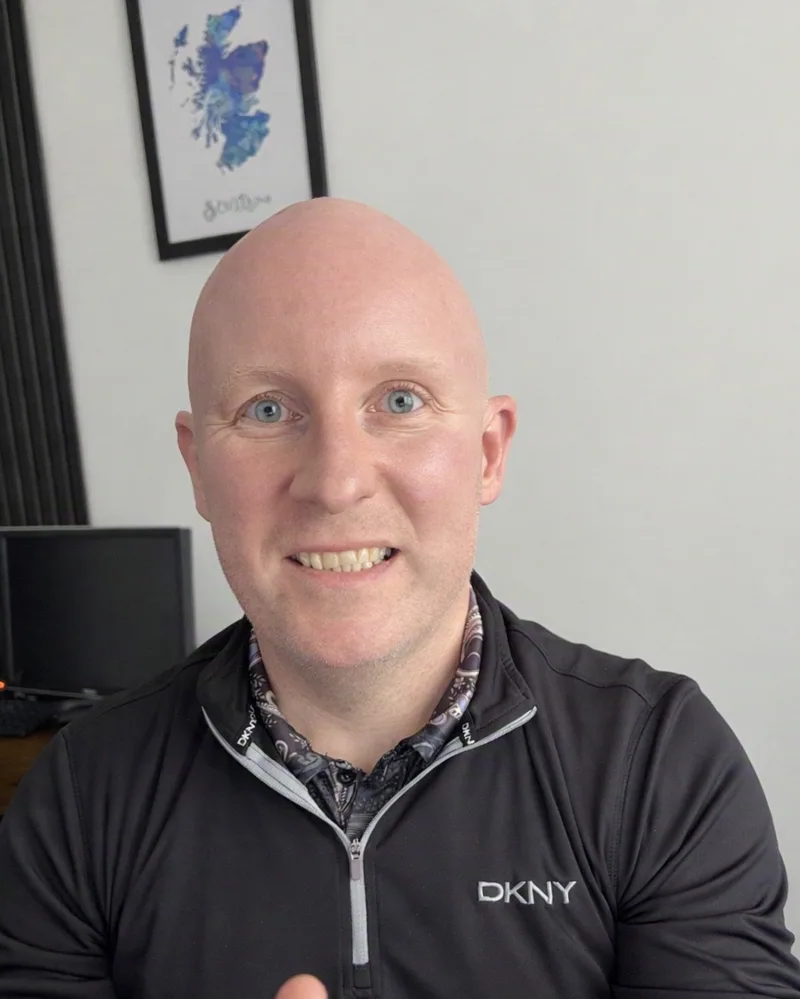
Meet your adviser
Hi, I'm Tony Flynn
I'm a mortgage and protection adviser based in Carluke, helping people across Lanarkshire and Scotland.
I've spent 15+ years in finance and have been named Mortgage Professional of the Year at the Prestige Awards Scotland five years in a row. I'll explain your options in plain English so you know exactly where you stand.
Agreement in principle questions
Can a mortgage be declined after agreement in principle?
Yes. An agreement in principle is not a guarantee of a mortgage. The lender still carries out a full check of your documents, credit file and the property before making an offer.
What should I do if my mortgage application is declined?
Find out the reason, avoid applying to lots of lenders at once, and speak to an adviser before you apply again. Tony can look at what happened and which lenders may be a better fit. Availability and criteria vary and nothing is guaranteed.
Does a declined application affect my credit score?
A full application can involve a credit search that may be visible to other lenders, and several applications in a short time can make lenders more cautious. That is why it helps to get advice before applying again.
Can I view a house without an agreement in principle?
You can usually arrange viewings without one. In Scotland, many homes are sold with a closing date, so having an agreement in principle can help show you are ready to move, but it is not a guarantee of a mortgage.
Can you help if I have been declined before?
Possibly. Some lenders may consider applications that others have declined, depending on your circumstances. Tony can look at the options with you.
Do you charge a fee for mortgage advice?
There may be a fee for mortgage advice. The amount depends on your circumstances. The fee is up to 1% but a typical fee is 0.3% of the amount borrowed. We will explain this before you commit.
Related guides
Ready to talk it through?
A quick chat with Tony is a good first step. No jargon, no pressure.
Talk to Tony