


Free Guide For Homeowners Remortgaging
Fixed Rate Ending Soon? Here’s What Actually Happens Next.
Worried about your payments going up? This guide covers what actually happens, plus debt consolidation, home improvements and extending your term, explained straight by a Lanarkshire broker.
Helping Lanarkshire homeowners manage their remortgage without the stress. Rated 5 stars by 235+ clients on Google.
Get The Free Remortgage Guide
Enter your name and email and we’ll send the PDF straight to your inbox.
By submitting this form you agree to our Privacy Policy and Terms & Conditions.
Getting ahead of your fixed rate ending
The earlier we start, the more room you've got to manage the new payment properly.
Chat 3 to 6 months before your deal ends
We compare staying put against your other options
Get a clear plan for your new payment
Handled through to your new rate starting
The options covered in the guide
Straight from the PDF, so you know exactly what you're getting before you hand over your email.
Product transfer vs remortgaging
The simple route of staying with your current lender, compared with properly comparing your options elsewhere.
Extending your term
How spreading what's left over more years affects your monthly payment, and what it costs you over time.
Overpayment flexibility
What your current deal might already let you do, before you assume you need a new one.
Home improvements and other debts
The honest considerations around releasing equity or folding other debts into your mortgage.
A straight answer before your rate jumps
15+ years doing this, based right here in Carluke, not a call centre.
- ✓Compares your options rather than defaulting to whoever you're already with
- ✓Explains what a longer term or overpayment flexibility actually costs you, not just the headline number
- ✓Talks through debt consolidation honestly, considerations not a hard sell
- ✓No pressure and no hard sell, just what's realistic for your situation
- ✓Here from that first chat through to your new rate starting
Remortgage questions, answered straight
When should I start looking at remortgaging?
Ideally 3 to 6 months before your current deal ends. That's when you've got the most room to compare your options properly, rather than reacting to whatever number comes through the letterbox.
Is it better to stay with my current lender or remortgage elsewhere?
It depends. Staying put with a product transfer is usually the simplest route and a sensible fallback, but it's rarely automatically the cheapest. Comparing your options elsewhere can genuinely move the needle on your new payment, it just takes a bit more paperwork and a fresh affordability check.
Can I extend my mortgage term to lower my payments?
Often, yes. Spreading what's left over more years can bring your monthly payment down, though you'll pay more interest overall and be paying it off for longer. Some lenders will let you shorten it again later if things improve, worth asking about upfront.
Should I fold other debts into my mortgage?
It's a considerations conversation, not a recommendation, every case is different. You'd be securing debt that was previously unsecured against your home, and spreading it over a mortgage term usually means paying more interest overall even though the monthly payment drops. Worth talking it through properly rather than deciding alone.
Can I release equity for home improvements when I remortgage?
Often, yes, if you're staying put and want the upgrade rather than the upheaval of moving. It affects your loan-to-value and can affect the rate you're offered, so it's worth working through the numbers first. Lenders usually want to know what the money's for, so have a rough plan ready.
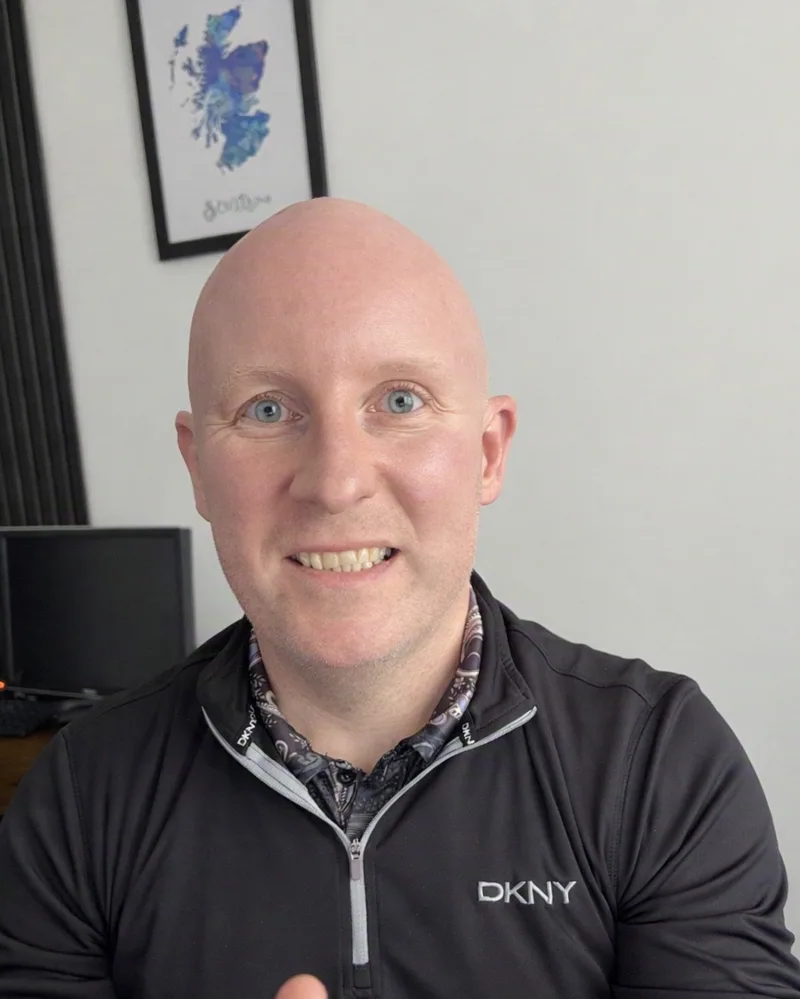
Meet your adviser
Hi, I'm Tony Flynn
I'm a mortgage and protection adviser based in Carluke, helping people across Lanarkshire and Scotland.
I've spent 15+ years in finance and have been named Mortgage Professional of the Year at the Prestige Awards Scotland five years in a row. I'll explain your options in plain English and search 28,000+ deals from over 100 lenders, so you know exactly where you stand.