


Free Guide For Self-Employed Applicants
Self-Employed And Buying? Here’s What Actually Matters.
One year’s accounts, going limited, and getting your income proof right, explained without the jargon by a Lanarkshire broker who works with self-employed clients every week.
Helping Lanarkshire’s self-employed buyers get a straight answer on what lenders actually want. Rated 5 stars by 235+ clients on Google.
Get The Free Self-Employed Guide
Enter your name and email and we’ll send the PDF straight to your inbox.
By submitting this form you agree to our Privacy Policy and Terms & Conditions.
Getting a self-employed mortgage sorted
Different from an employed application, not harder, once it's set up right.
Chat about how your business is structured
We work out which lenders actually fit your figures
Get your income proof ready in advance
Apply with the right lender first time
What the guide actually covers
Straight from the PDF, so you know exactly what you're getting before you hand over your email.
Only one year's accounts?
Why that doesn't automatically rule you out, and what lenders actually look for instead.
Sole trader to limited company
How switching structure changes the way a lender reads your income, and why timing matters.
Income proof, sorted early
Exactly what to have ready, SA302s, accountant's reference, business bank statements, before we even start.
Practical tips that save time
The small things that hold self-employed applications up, and how to avoid them.
Self-employed doesn't mean harder
15+ years including a background in banking, based right here in Carluke.
- ✓Works with self-employed clients every week, sole traders and limited company directors
- ✓Knows which lenders actually consider one year's accounts
- ✓Compares your options rather than pushing whoever's easiest
- ✓Explains the process in plain English, no jargon
- ✓Here from that first chat right through to getting the keys
Self-employed mortgage questions, answered straight
Can I get a mortgage with only one year's accounts?
Often, yes, particularly if you were doing the same job employed or in the same trade beforehand. A consistent, provable income pattern matters more than the calendar here. It's genuinely case by case, worth a proper conversation before you assume either way.
Should I go limited before I apply for a mortgage?
Timing matters. As a sole trader, lenders generally look at your net profit. As a limited company director, some look at salary plus dividends, others also consider retained profit, it varies by lender. Switch structure right before applying and your provable income on paper can look lower for a while, even if the business is doing fine. Talk to me about the order of operations before you do either.
What income proof will I need?
Usually SA302s and tax year overviews from HMRC for the last two years, sometimes one, an accountant's reference, and a few months of business bank statements. Limited company directors will also need company accounts and confirmation of salary and dividends drawn.
Do I need a specialist self-employed mortgage lender?
Not necessarily a specialist product, but specialist knowledge of which lenders' self-employed criteria actually fits your figures. It varies a lot between lenders, and knowing who to go to first can save you a rejection on your file.
What's the biggest thing that holds up self-employed applications?
Late or missing accounts and tax returns, and major structural changes made right before applying without planning the timing. Get your accountant's reference sorted early and keep your filings up to date, and it moves a lot quicker.
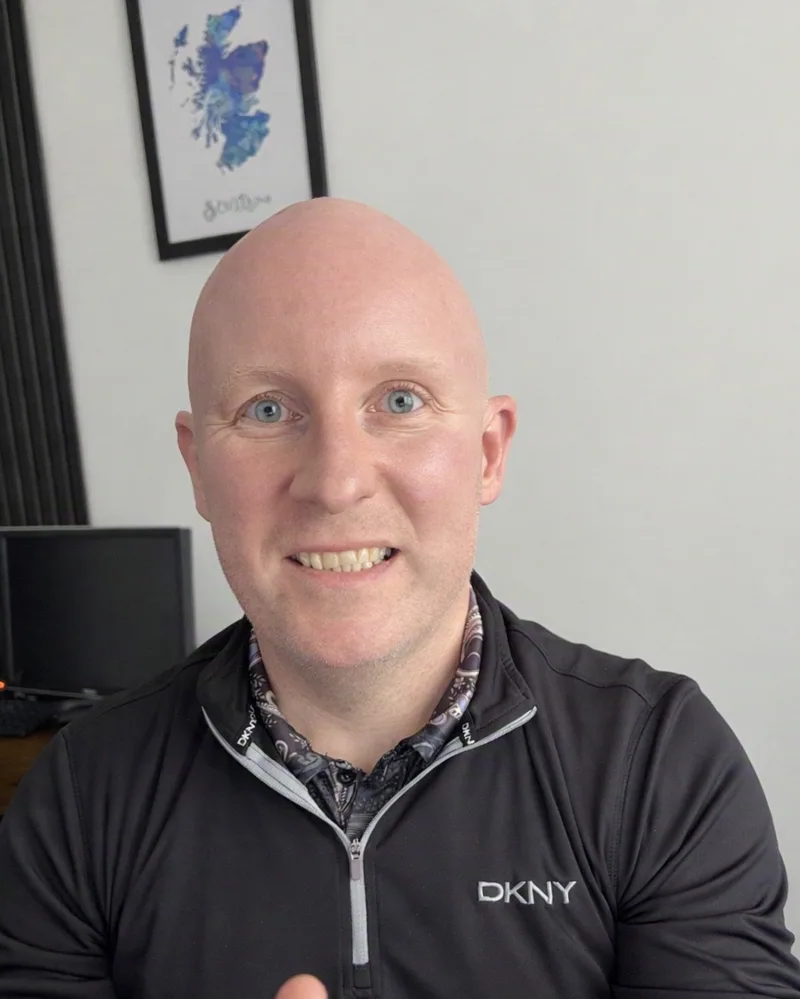
Meet your adviser
Hi, I'm Tony Flynn
I'm a mortgage and protection adviser based in Carluke, helping people across Lanarkshire and Scotland.
I've spent 15+ years in finance and have been named Mortgage Professional of the Year at the Prestige Awards Scotland five years in a row. I'll explain your options in plain English and search 28,000+ deals from over 100 lenders, so you know exactly where you stand.