


Free Guide To Protecting Your Family
If Something Happened To You, Would Your Family Be OK?
The honest, unglamorous conversation about protecting your family and your home, from a Lanarkshire broker who has it more often than you’d think.
Helping Lanarkshire families close the gaps in their cover, with no pressure and no hard sell. Rated 5 stars by 235+ clients on Google.
Get The Free Protection Guide
Enter your name and email and we’ll send the PDF straight to your inbox.
By submitting this form you agree to our Privacy Policy and Terms & Conditions.
Getting your cover sorted properly
A straightforward conversation, no pressure, no hard sell.
Quick chat about what you've already got
We check it still matches your life now
See exactly where the gaps are, if any
Get cover that actually fits
What the guide actually covers
Straight from the PDF, so you know exactly what you're getting before you hand over your email.
Life cover
Decreasing versus level cover, and which usually makes sense if the mortgage is the main thing you're protecting.
Income protection
How it replaces a portion of your income if you can't work, and why it's worth a proper look if you're self-employed.
The gaps people don't realise they have
Critical illness cover, family income benefit, and cover that's quietly gone out of date.
When to review what you've already got
The life changes that mean your existing cover might not match your circumstances anymore.
An honest, unglamorous conversation
I've sat across from enough families to know it's worth ten minutes of your time.
- ✓No pressure and no hard sell, just an honest look at what you need
- ✓Reviews cover against your life now, not what it looked like when you first took it out
- ✓Explains the options in plain English, no jargon
- ✓Based right here in Carluke, not a call centre
- ✓Here whenever your circumstances change, new baby, new mortgage, new job
Protection and cover questions, answered straight
Do I actually need life cover if I already have a mortgage?
Worth checking rather than assuming either way. Decreasing cover tracks your mortgage balance down as you pay it off and is usually the cheaper option if the mortgage is the main thing you're protecting. Level cover stays the same throughout, worth it if you want the payout to cover more than just the mortgage.
What's the difference between life cover and income protection?
Life cover pays out if you die. Income protection replaces a portion of your income if you can't work due to illness or injury, while you're still very much alive. Most people think about the first and forget the second, it's especially worth a proper look if you're self-employed or your employer's sick pay wouldn't stretch far.
When should I review my existing cover?
Any time your circumstances change, a new baby, a bigger mortgage, a new partner, a new job. Cover that matched your old mortgage or your old life might not match where you are now. A quick review costs nothing and either turns up a gap or gives you peace of mind that you're already sorted.
What's family income benefit?
It pays an ongoing income to your family rather than one lump sum, which can suit families with young kids well, since it mirrors the income you'd have brought in rather than landing all at once.
Is this going to be a hard sell?
No. It's a straightforward conversation. We look at what you've got, what you actually need, and whether there's a gap worth closing. No pressure, no hard sell, and if everything already fits, I'll tell you that too.
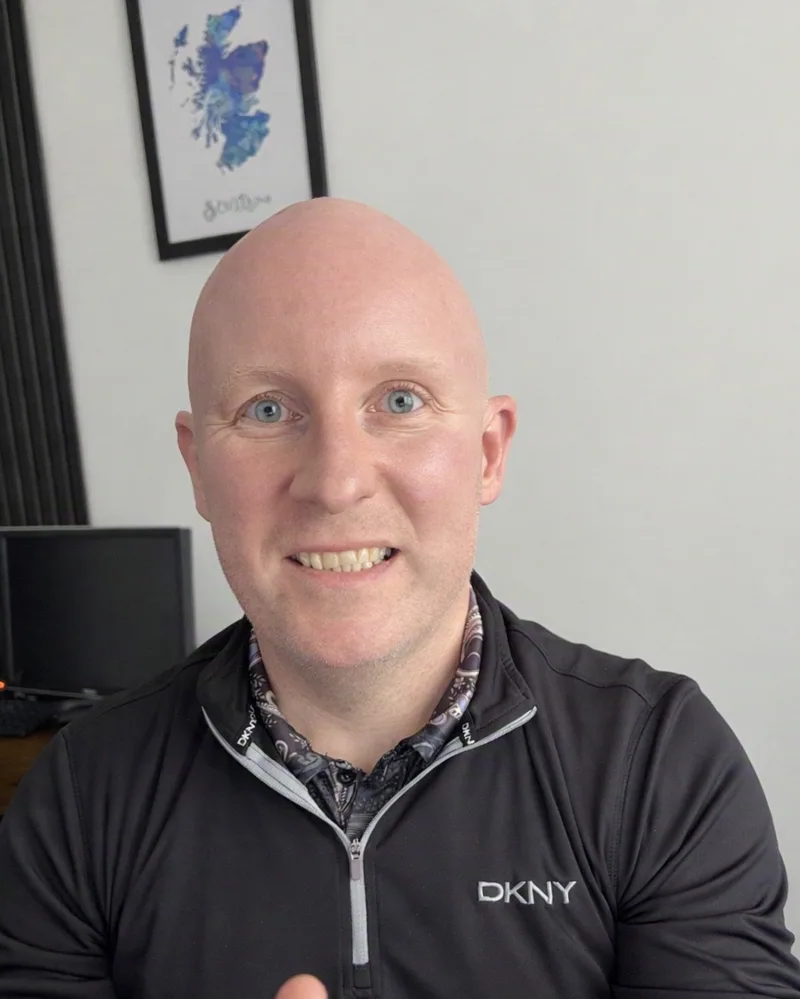
Meet your adviser
Hi, I'm Tony Flynn
I'm a mortgage and protection adviser based in Carluke, helping people across Lanarkshire and Scotland.
I've spent 15+ years in finance and have been named Mortgage Professional of the Year at the Prestige Awards Scotland five years in a row. I'll explain your options in plain English and search 28,000+ deals from over 100 lenders, so you know exactly where you stand.